Buying
Rent to Own in Dubai (2026): How It Works, Costs and Risks
By Dhananjay Arora · CEO & Founder, Al Ranim Properties
Published 20 October 2026 · 9 min read
Rent to own could be the ideal solution. You take up residence, pay close to rent and at a later date own the property. Rent to own does exist in Dubai but operates in a slightly different way to that advertised. Below is the information on how rent to own actually operates, the fees involved and tips on how to make sure you are protected.
Key takeaways
- Rent to own is allowed in Dubai and there is registration available through the Dubai Land Department. However the number of genuine rent to own transactions is quite limited.
- There is no specific rent to own law. It will be outlined within the agreement as to how much of the rent goes into the purchase price and what is forfeited should the lease be terminated.
- An unregistered rent to own agreement is simply an agreement between the parties and does not confer any interest in land.
- Both conventional mortgages and bank Islamic lease to own mortgages (Islamic home finance) require a minimum 20% deposit for most expats purchasing first time property.
The short answer
Rent to own is allowed in Dubai however only certain banks and developers currently provide this option. The terms vary between each agreement and registration through the Dubai Land Department provides a level of protection.
What Is Rent to Own in Dubai?
Rent to own (or lease to own) is an arrangement whereby the tenant occupies a property and pays rent on a monthly or quarterly basis. A proportion or all of the rent paid goes towards the purchase of the property. At the end of the agreement the buyer can purchase the property or in some agreements the tenant can terminate the agreement.
What rent to own is
- Right or obligation to purchase the property at the end of the lease
- Agreed instalment payments adding up to the purchase price
- Agreed transaction registered with the Dubai Land Department and allowing the issue of a conditional title until full payment is made
What it is not
- Off plan arrangement where the buyer already owns the property and pays in instalments
- Rent instalment plans such as Flexi Rent or other arrangements that only split the rent and do not confer any ownership
- Oral agreement from landlord allowing future purchase
Is Rent to Own Legal in Dubai?
There is no specific law in Dubai for rent to own. Rent to own arrangements are captured under the property registration law (Law No. 7 of 2006). This law states that any agreement that results in the creation or transfer of property rights is only valid if the agreement is registered with the Dubai Land Department. The Dubai Land Department has indicated that rent to own only applies to freehold properties and allows issue of a title conditional on payment until the property is fully purchased.
Before you pay: Request proof of registration prior to payment. This can be in the form of the provisional lease-to-own e-contract issued by the Dubai Land Department or the title deed. Without these you only have a private agreement and the amount paid may not be protected.
Types of Rent to Own Deals in Dubai
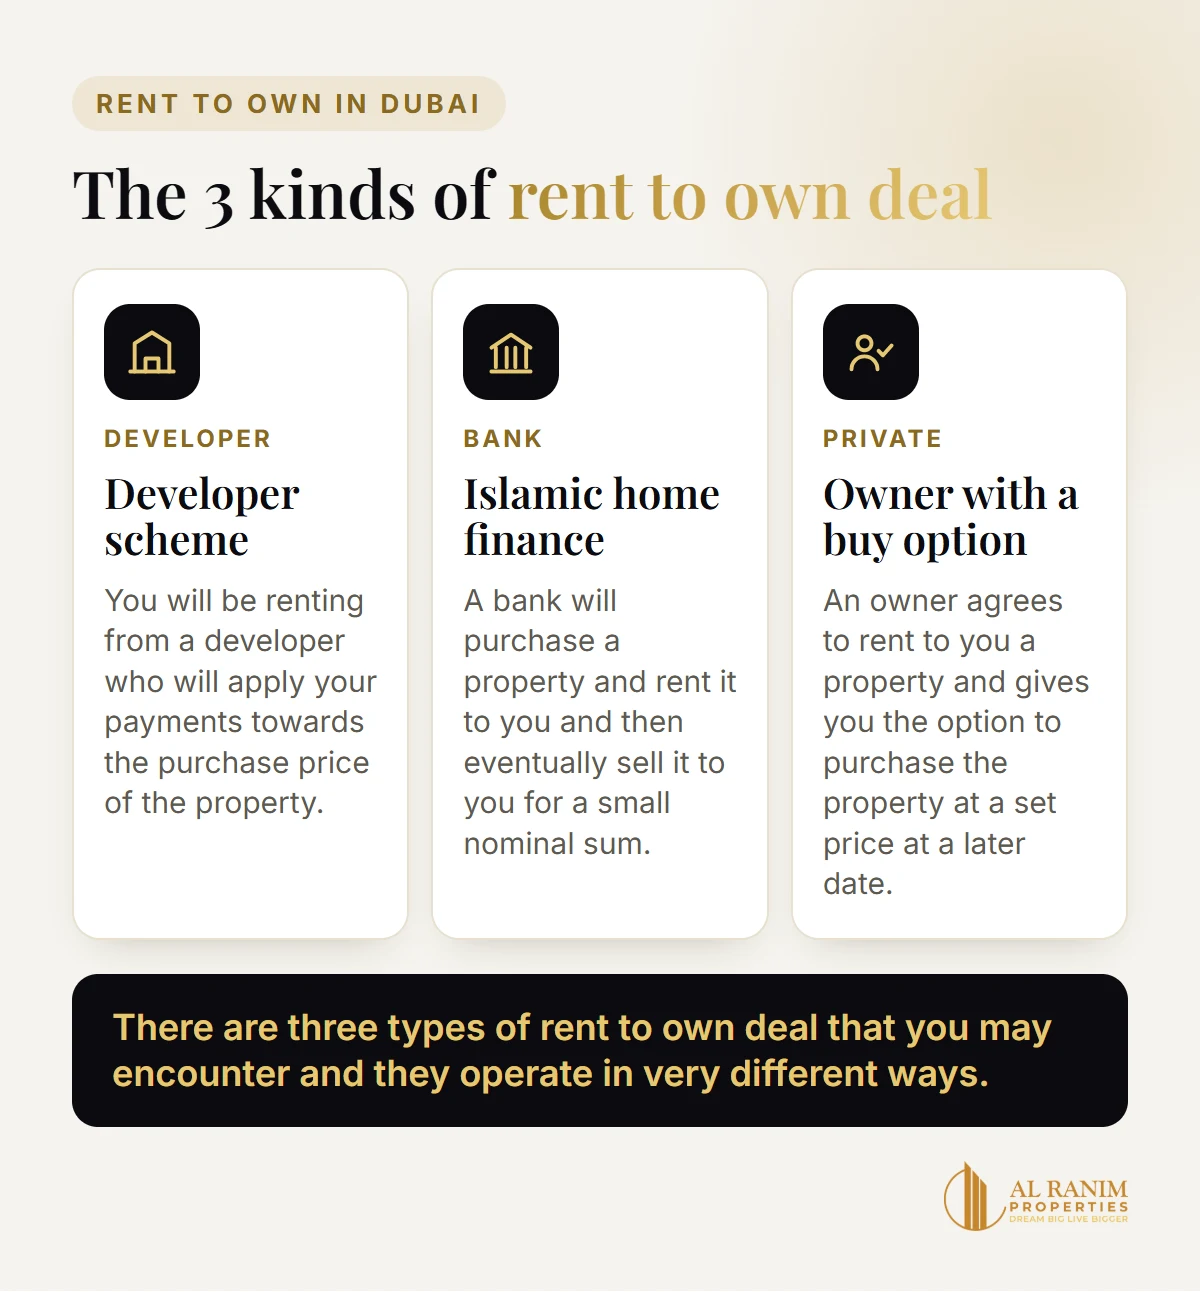
- Developer schemes: Dubai South Properties promoted a ten year rent to own scheme at The Pulse in August 2020 that was completely rent to own with no deposit and no requirement to purchase. This type of rent to own is no longer commonly promoted by developers.
- Islamic home finance: Islamic home finance in the UAE operates as rent to own. ADIB, Emirates Islamic and Dubai Islamic Bank all operate on this basis with a standard deposit and credit check.
- Owner with a buy option: This can be a viable option as long as it is registered with the Dubai Land Department and contained in the contract with all terms stated.
How Rent to Own Works in Dubai: Step by Step
All contracts vary but a registered rent to own transaction in Dubai typically involves the following five steps.
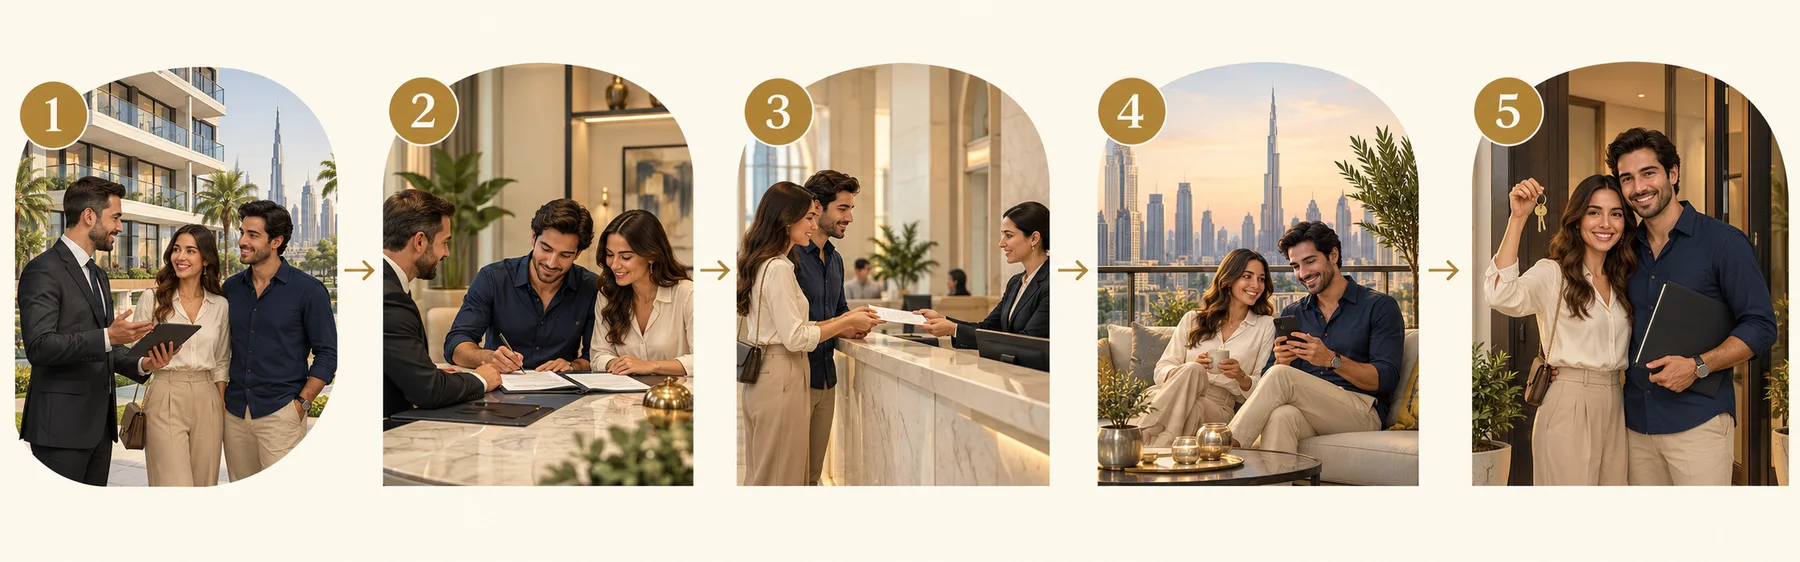
- Find the home. Locating a freehold property with a developer, bank or owner who is offering a rent to own transaction and agreeing a purchase price, length of transaction and the proportion of payments applied to the purchase price.
- Sign the contract. Entering into a contract that details the purchase price, length of the transaction, payment terms, service charges and fees, early termination clauses and other specific terms.
- Register it. Registration at a trustee centre for a full lease to own transaction or via the developer's online portal Oqood for a transaction from a developer.
- Live and pay. Check all your payments are correctly recorded as agreed and start making your payments as agreed upon.
- Own it. At the end of the transaction period the balance can be paid in cash or via mortgage and the property title will be registered in your name by the Dubai Land Department.
Rent to Own Costs: What You Pay to Register the Deal
The Dubai Land Department provides information on the registration charges for a rent to own transaction on their service page. The main charge is a transfer fee of 4% of the transaction value (in the same way as a standard transaction) split as 2% for the seller and 2% for the buyer. Using these publicly available charges we have calculated the charges for three typical transaction values.
| Fee (AED) | AED 750,000 home | AED 1,200,000 home | AED 2,000,000 home |
|---|---|---|---|
| Transfer fee (4%, paid by the buyer in practice) | 30,000 | 48,000 | 80,000 |
| Title deed | 580 | 580 | 580 |
| Trustee centre fee (AED 4,000 + VAT) | 4,200 | 4,200 | 4,200 |
| Map fee | 225 | 225 | 225 |
| Knowledge and innovation fees | 20 | 20 | 20 |
| Conveyancing fee (AED 3,500 + VAT) | 3,675 | 3,675 | 3,675 |
| Agency fee (2% + VAT, at signing) | 15,750 | 25,200 | 42,000 |
| Fee on the rental value | 0.25% or 2% of rent | 0.25% or 2% of rent | 0.25% or 2% of rent |
| Total (before the rent fee) | AED 54,450 | AED 81,900 | AED 130,700 |
| Share of the price | 7.3% | 6.8% | 6.5% |
Our calculation from the Dubai Land Department's Lease To Own registration service page (read 20 Oct 2026). The page lists 2% for the seller, 2% for the buyer and AED 250 for the title deed; on transfer day the buyer normally pays the full 4% and AED 580. Trustee fee is AED 2,000 + VAT under AED 500,000. If a bank finances the deal, add mortgage registration of 0.25% of the amount financed and a conveyancing fee of AED 6,600 + VAT.
Agency fee: Our agency fee is 2% of price plus VAT, at the time of execution and registration of the rent to own agreement on the same basis as normal resale. For a scheme with a developer, it is more common for the developer to pay the agent. For a private lease option with an unregistered sale at inception, a common arrangement is 5% of the annual rent at the execution of the lease and 2% of the transaction price at completion.
Who pays: Typically the entire charge of 4% is borne by the lessee in Dubai, however this is governed by the agreement. The Dubai Land Department has charges based on the rental value. On one of their pages this charge is 0.25% and on another it is 2%. Please check with the Dubai Land Department prior to signing.
Rent to Own vs Renting vs Buying With a Mortgage
Rent to own is a transaction between a rent only transaction and a buy transaction. The major points that distinguish these transactions are ownership of the property during the transaction, the amount of cash at the start of the transaction and the amount at stake should the transaction fall through.
| Renting | Rent to own | Islamic home finance | Mortgage | |
|---|---|---|---|---|
| Who owns the home during the deal | The landlord | The seller, until you pay in full | The bank, until the end | You, with the bank's mortgage registered |
| Cash on day one | Rent, security deposit, agency fee | Set by the contract, sometimes none | At least 20% plus fees | At least 20% plus fees |
| Monthly payment | Market rent | Often above market rent | Lease payments to the bank | Loan instalments |
| If you leave early | Your tenancy notice terms | Usually lose the option fee and rent credited | Early settlement up to 1% or AED 10,000 | Sell, early settlement up to 1% or AED 10,000 |
20% is the UAE Central Bank minimum for an expat first home under AED 5 million. Early settlement figures: UAE Central Bank cap and ADIB key facts statement (Aug 2025). Rent-to-own terms vary by contract.
Risks of Rent to Own in Dubai
Most issues surrounding rent to own arise due to the agreement rather than the nature of the transaction. These are the issues we find the most.
Unregistered deals
An unregistered transaction with the Dubai Land Department does not represent a recognised right in property in Dubai. A claim could only be made against the other party in a private personal matter.
Leaving early
Should a transaction fall through (by not purchasing or by ceasing to make payments) the option payment and any rent paid is typically lost unless otherwise provided in the agreement. Please read the exit provisions twice.
Higher monthly cost
With rent to own arrangements, the payment for a given property is typically in excess of the market rental for that property. You are moving toward ownership, but you pay extra for it each month.
Disputes go to court
The Rental Disputes Centre will not deal with disputes involving long leases or lease finance agreements registered under the property registration system. These disputes must be submitted to the Dubai Courts which are slower and more expensive.
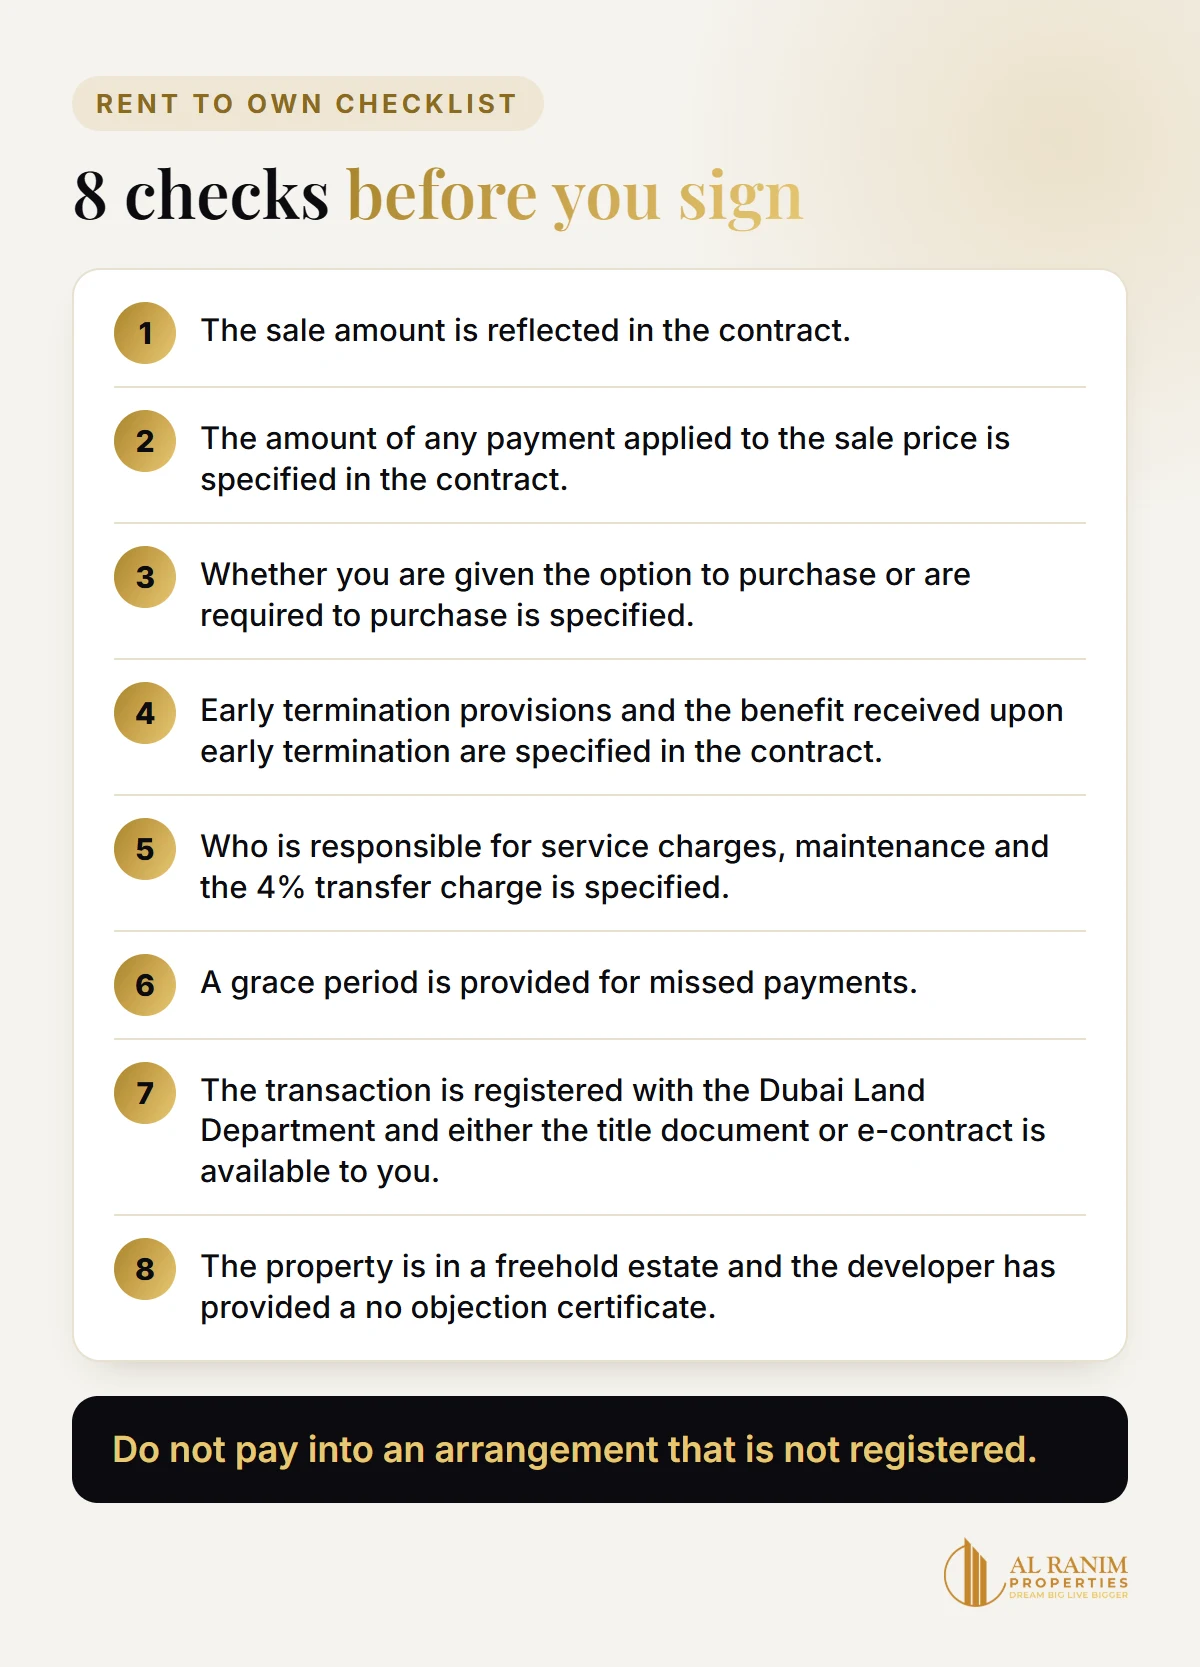
Rent to Own Checklist: 8 Things to Check Before You Sign
See this list prior to signing any document.
Who Should Consider Rent to Own?
Rent to own may suit some people but can be expensive for others.
It can suit you if
- You intend to rent the property for a substantial period.
- You have a regular income but do not yet have the 20% deposit required by a bank.
- You have discovered a registered scheme with defined exit provisions and a fixed sale price.
Think twice if
- You are likely to move jobs or exit Dubai in the near future.
- You have a deposit saved and can obtain a mortgage (which are often available at a lower rate).
- The seller will not register the sale or put the terms of the agreement in writing.
Alternatives to Rent to Own in Dubai
Not offering rent to own on the property you are interested in? There are other options available. Dubai first time home buyer programme is for UAE residents 18 years old and over with no freehold property in Dubai for property under AED 5 million. Advantages include paying the Dubai Land Department fees in instalments, preferential off plan prices and more. Off plan payment plans mean you can pay as the building progresses. For an expat first time home under AED 5 million a mortgage requires a minimum 20% deposit.
The bottom line
- Rent to own is permitted in Dubai and can be registered with the Dubai Land Department.
- The terms of how much of your rent goes in to the property and what is forfeited upon termination are set within the contract and not by law.
- Do not pay into an arrangement that is not registered.
- Compare rent to own with a mortgage and the First Time Home Buyer Programme prior to making a decision.
Interested in purchasing a property in Dubai that you can own? We can assist in viewing both off plan and ready to move in properties. We can advise on the payment options and check any rent to own arrangement prior to agreement. All our staff are licensed.
Al Ranim Forum
Have a question about Dubai property?
Ask the community and our licensed team about buying, renting or selling in Dubai. No account needed.
FAQ
Frequently asked questions
Yes. Rent to own is allowed in Dubai and the Dubai Land Department will register rent to own agreements. However there are very few genuine rent to own agreements so typically either a payment plan or mortgage is taken.
Only with a developer that finances the deal itself. An example of a developer providing rent to own is Dubai South for The Pulse in 2020. For mortgage lenders, the Central Bank has guidelines which require a minimum of 20% deposit for most first time expat buyers for properties under AED 5 million.
We were unable to find a current rent to own agreement from Emaar via their website. Emaar provides payment plans but these are a form of instalment purchase and are not a lease.
Islamic home finance products provided by banks in the UAE are lease to own products and have been approved by the Sharia committee in each bank. A developer arrangement or private arrangement can be Islamic if the contract allows for it.
This varies according to the contract. In general the rent that has been paid and the option fee will be lost. For off plan agreements these will fall under the current default provisions set out in Dubai Law No. 19 of 2017. For bank finance there is also a risk of losing the property and damage to your credit history.
An agreement can be registered with the Dubai Land Department and a title deed can be issued against a payment plan. Once the total sum has been paid the final title deed can be issued in the buyer's name.
The Dubai Land Department will register lease to own deals for both residents and non-residents. For non residents a passport is used rather than an Emirates ID. There are also conditions set by developers and banks.
Work with Al Ranim Properties
Found this useful? Talk to a consultant about your own situation.